Why Chronic Condition Coverage Is Critical for UAE Expats
Living with a chronic condition like diabetes, hypertension, asthma, or heart disease as an expat in the UAE brings unique healthcare challenges. Unlike your home country where you may have had established relationships with specialists and predictable healthcare costs, managing chronic conditions in the UAE requires navigating a complex insurance landscape where coverage, costs, and provider networks vary dramatically between plans.
According to the International Diabetes Federation, the UAE has one of the highest diabetes prevalence rates in the world — approximately 16.3% of the adult population. The rate among long-term expat residents is estimated at 12-14%, driven by lifestyle changes, dietary habits, and the stress of expatriate life. Hypertension affects roughly 28% of the UAE’s adult population, and chronic respiratory conditions are common due to the desert climate and air quality factors.
For expats living with these conditions, choosing the right health insurance plan is not just a financial decision — it directly impacts your quality of life, your ability to access specialists, and your long-term health outcomes. This guide covers everything you need to know about health insurance coverage for chronic conditions in the UAE, including diabetes management, specialist access, medication coverage, and practical strategies for getting the best care within your insurance plan.
How UAE Insurance Treats Pre-Existing and Chronic Conditions
Understanding how UAE health insurance classifies and covers chronic conditions is the first step in choosing the right plan.
Pre-Existing Condition Defined
A pre-existing condition is any medical condition that existed before the start of your insurance policy. This includes conditions you have been diagnosed with, received treatment for, or shown symptoms of — even if you were never formally diagnosed. When you apply for insurance in the UAE, you are typically required to complete a medical declaration form disclosing your health history.
Waiting Periods for Chronic Conditions
Most health insurance plans in the UAE impose a waiting period for pre-existing chronic conditions — typically 6 to 12 months. During this period, any claims related to your declared chronic condition will be denied. However, some premium comprehensive plans offer coverage from day one for common chronic conditions like diabetes and hypertension, usually at a higher premium.
DHA Regulations on Chronic Conditions
The Dubai Health Authority has mandated that all insurance plans — including the minimum Essential Benefits Plan — must cover certain chronic conditions after a maximum waiting period. However, the coverage level, network restrictions, and medication formularies differ significantly between basic and comprehensive plans. In Abu Dhabi, the Department of Health (DoH) has similar requirements under the unified healthcare plan regulations.
What Happens If You Do Not Disclose a Chronic Condition
Failing to disclose a known chronic condition during enrollment can result in claim denial, policy cancellation, and in some cases, being blacklisted by insurers. UAE insurers have access to medical records through the national health information exchange systems, so non-disclosure is both risky and potentially discoverable. Always be honest on your medical declaration form — it protects you legally and ensures your coverage is valid when you need it.
Diabetes Management Coverage in UAE Insurance Plans
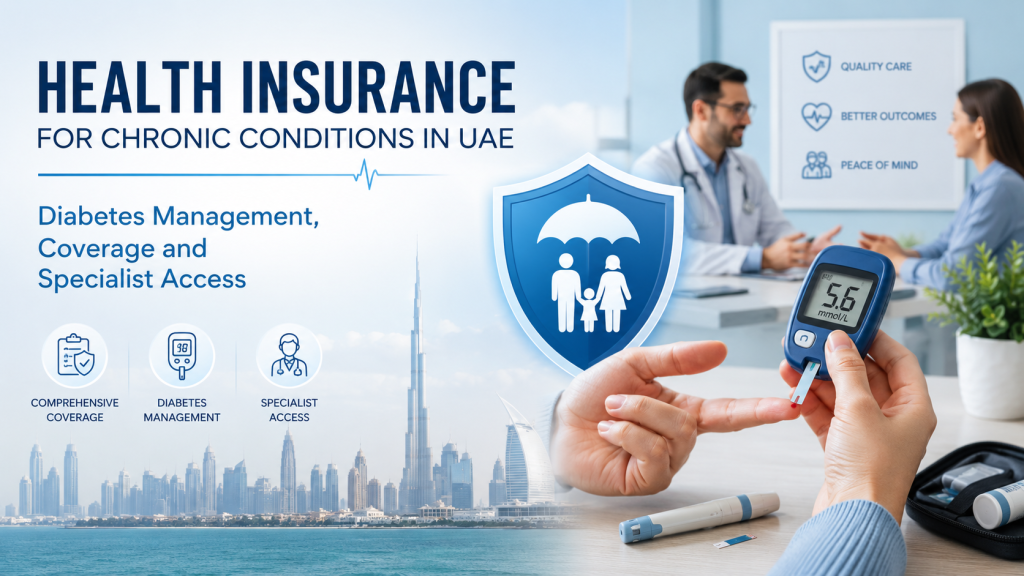
Diabetes is the most common chronic condition among UAE residents, and insurance coverage for diabetes management varies significantly across plans. Here is what you need to know:
What Good Diabetes Coverage Includes
- Endocrinologist consultations: Regular specialist visits for managing blood sugar levels, medication adjustments, and complication monitoring
- HbA1c testing: Quarterly blood tests that measure your average blood sugar level over 3 months — the gold standard for diabetes monitoring
- Continuous glucose monitoring (CGM): Some premium plans cover devices like FreeStyle Libre or Dexcom systems
- Insulin and oral medications: Coverage for prescribed diabetes medications including insulin pens, metformin, and newer drugs like GLP-1 receptor agonists
- Diabetic supplies: Test strips, lancets, glucose meters, insulin syringes
- Diabetic foot care: Podiatry consultations and annual diabetic foot assessments
- Retinal screening: Annual eye examinations to detect diabetic retinopathy
- Nutritionist/dietitian: Some comprehensive plans include sessions with a clinical dietitian for diabetes management
Typical Costs for Diabetes Management in UAE Without Insurance
| Service | Estimated Annual Cost (AED) |
|---|---|
| Endocrinologist visits (4 per year) | 2,000–4,000 |
| HbA1c tests (4 per year) | 800–1,600 |
| Complete blood panel | 500–1,200 |
| Insulin (monthly supply) | 3,600–7,200 |
| Oral medications (metformin etc.) | 1,200–3,600 |
| Test strips and supplies | 1,800–3,600 |
| Retinal screening | 500–1,000 |
| Foot care assessment | 300–600 |
| Total annual cost | 10,700–22,800 |
For a diabetic expat without insurance, managing the condition properly can cost AED 10,000 to AED 23,000+ per year. With good insurance coverage and typical 20% copay, the out-of-pocket cost drops to approximately AED 2,000–5,000 per year — a massive savings that makes comprehensive insurance a financial necessity for diabetic patients.
Best Insurance Plans for Chronic Conditions in UAE
Based on coverage breadth, specialist network, medication formularies, and our research of policyholder experiences, here are the top insurance options for expats with chronic conditions:
1. Cigna HealthGuard – Comprehensive Plan
- Chronic condition waiting period: 6 months (some conditions from day one)
- Specialist access: Direct access to endocrinologists, cardiologists, and pulmonologists without GP referral
- Medication coverage: Extensive formulary including newer biologic medications
- Annual limit: AED 1,000,000+
- Chronic condition management sub-limit: No separate sub-limit — covered under overall limit
- CGM devices: Covered on gold plan
2. AXA Gulf – Enhanced Plan
- Chronic condition waiting period: 6–12 months depending on condition
- Specialist network: Strong UAE-wide network of 700+ providers
- Medication coverage: Good formulary with generic alternatives
- Lab tests: Covered for monitoring chronic conditions
- Wellness programs: Includes chronic disease management programs
3. Daman – National Health Insurance
- Strong Abu Dhabi network: Particularly good for residents in Abu Dhabi
- Chronic disease programs: Daman’s Hayakum program offers diabetes management support
- Thiqa plans: Enhanced Thiqa covers chronic conditions from enrollment
- Cost: Competitive pricing for comprehensive chronic condition coverage
4. BUPA Global (Now Cigna International)
- Best for: Expats who need chronic condition coverage plus international treatment access
- Covers treatment abroad: If you need specialist treatment not available in UAE
- Comprehensive medication coverage: Including specialist medications not widely available in UAE
Case Study: Managing Type 2 Diabetes as an Expat in Dubai
Rajesh, a 42-year-old Indian expat working as an IT manager in Dubai, was diagnosed with Type 2 diabetes three years ago in India before relocating to the UAE. When he moved to Dubai, his employer provided a basic health insurance plan that covered hospitalization only.
The problem: On the basic plan, Rajesh’s endocrinologist visits, HbA1c tests, metformin medication, and quarterly blood work were all out of pocket — costing him approximately AED 14,000 per year. He started skipping specialist visits and stretching his medication to save money, which caused his HbA1c to rise from 7.1% to 8.5% — entering the poorly controlled range.
The solution: Rajesh switched to Cigna’s comprehensive plan with his employer’s approval, paying the premium difference of AED 7,200 per year. The plan covered his endocrinologist, quarterly testing, and medications with a 20% copay.
Results after 12 months:
- Regular endocrinologist visits (4 per year): Covered after 20% copay — AED 640 instead of AED 3,200
- HbA1c and blood tests: Covered — AED 320 instead of AED 1,600
- Metformin + sitagliptin medication: Covered — AED 960 instead of AED 4,800
- Diabetic retinal screening: Covered — AED 120 instead of AED 600
- Total out-of-pocket: AED 2,040 (vs. AED 14,000 previously)
- HbA1c improved from 8.5% back to 6.9% (well-controlled)
- Annual savings: AED 4,760 after premium difference
More importantly, Rajesh’s diabetes was back under control, reducing his long-term risk of complications like kidney disease, nerve damage, and cardiovascular problems — complications that would cost exponentially more to treat.
Tips for Maximizing Chronic Condition Coverage
1. Always Declare Your Conditions Honestly
Non-disclosure is the number one reason for claim denial in UAE health insurance. Declare everything — even conditions you consider mild or controlled. It is better to have a declared condition with a waiting period than to risk having all your claims denied for non-disclosure.
2. Ask About Disease Management Programs
Many UAE insurers offer chronic disease management programs that provide additional support including health coaching, medication reminders, regular monitoring, and nutritional guidance. These programs are usually free for enrolled members and can significantly improve your health outcomes.
3. Understand Your Medication Formulary
Each insurer has an approved list of medications (formulary) that they cover. Before enrolling, check if your specific medications are on the formulary. If your doctor prescribes a brand-name drug and a generic equivalent is available, your insurer may only cover the generic version. Discuss medication options with your doctor to find covered alternatives if needed.
4. Build a Relationship with Your Specialist
Having a consistent specialist who knows your medical history is invaluable for chronic condition management. When choosing a plan, check if your current or preferred specialist is in-network. If you change plans, ask if the new insurer’s network includes specialists experienced in your specific condition.
5. Keep Detailed Medical Records
Maintain copies of all your medical reports, lab results, prescriptions, and specialist letters. When switching insurers or renewing your policy, these records help ensure continuity of care and can support pre-authorization requests for treatments and medications.
Frequently Asked Questions
Does UAE health insurance cover diabetes medication and insulin?
Yes, most comprehensive health insurance plans in the UAE cover diabetes medications including insulin, metformin, and other prescribed drugs after the applicable waiting period. Coverage is subject to the insurer’s medication formulary, and you may need to use generic alternatives if available. Basic plans may have limited medication coverage with higher copays.
Can I get health insurance in UAE with a pre-existing heart condition?
Yes, you can obtain health insurance with a pre-existing heart condition in the UAE. Most comprehensive plans will cover pre-existing cardiac conditions after a waiting period of 6 to 12 months. Some premium plans offer day-one coverage at a higher premium. You must disclose your heart condition during enrollment to ensure valid coverage.
What is the waiting period for chronic condition coverage in UAE insurance?
The typical waiting period for chronic condition coverage in UAE health insurance ranges from 6 to 12 months depending on the insurer and the specific condition. Some premium comprehensive plans offer reduced waiting periods of 3-6 months or even day-one coverage for common chronic conditions. DHA regulations now require coverage after maximum 6 months for certain conditions.
Does basic insurance in Dubai cover chronic disease management?
Basic insurance plans in Dubai provide limited chronic disease coverage, primarily covering emergency situations and basic medication after the waiting period. However, specialist consultations, advanced lab tests, disease management programs, and newer medications are typically not included in basic plans. For proper chronic disease management, a comprehensive plan is strongly recommended.
Can my insurer refuse to renew my policy because of a chronic condition?
Under DHA and DoH regulations, insurers in the UAE generally cannot refuse to renew a policy solely because of a chronic condition that was properly disclosed at enrollment. However, premium increases at renewal are possible. If your insurer attempts to refuse renewal or impose unreasonable premium increases, you can file a complaint with the relevant health authority.
Conclusion: Prioritize Your Health, Protect Your Finances
Managing a chronic condition as an expat in the UAE requires a proactive approach to both healthcare and insurance. The right health insurance plan does not just save you money — it ensures you have consistent access to specialists, proper medication, regular monitoring, and disease management support that keeps your condition under control.
Whether you are living with diabetes, hypertension, asthma, or any other chronic condition, investing in comprehensive health insurance is one of the most important financial and health decisions you can make. The cost of untreated or poorly managed chronic conditions — both in terms of money and long-term health consequences — far exceeds the premium difference between a basic and comprehensive plan.
Take the time to compare plans, check specialist networks, understand medication formularies, and choose a plan that supports your specific health needs. Your future self will thank you for making this investment in your health today.
Related Articles You May Find Helpful
- Top health insurance companies in UAE
- Health insurance claim process in UAE
- Comprehensive vs basic health insurance
- Switching health insurance providers in UAE
- Factors influencing health insurance premiums
Useful External Resources
Disclaimer: This article is for informational purposes only and does not constitute medical or insurance advice. Chronic condition coverage varies between insurers and plan tiers. Always consult your healthcare provider for medical decisions and a licensed insurance broker for personalized insurance recommendations.